RegTech in Banking: Why It’s Important
What's new: Current market data, the EU rules now shaping bank compliance (AMLA, DORA, instant payments, MiCA, AI Act), recent fines, use cases, build vs buy, costs, a checklist, AI and an FAQ.
Summarize with AI
Read summarized version with AI
- RegTech is technology that helps financial institutions meet regulatory requirements: onboarding, AML monitoring, screening, reporting, resilience and data protection.
- The market keeps growing: Fortune Business Insights values it at $19.06 billion in 2025 and expects $23.43 billion in 2026, with financial services the largest segment.
- Banks face several changes at once: AMLA and a single AML rulebook from 2027, DORA since January 2025, instant payments with verification of payee since October 2025, MiCA and AI Act rules for credit scoring.
- Enforcement targets process failures RegTech is built for, from FinCEN's record $1.3 billion fine on TD Bank in 2024 to the FCA's £21.1 million fine on Monzo in 2025.
- Most banks buy commodity checks, build orchestration, scoring and reporting around them, and measure results in onboarding time, analyst hours and audit findings.
Banks spend more on compliance every year, and supervisors expect more of it to be automated, traceable and fast. RegTech, short for regulatory technology, is how banks and fintechs meet that expectation without hiring a compliance analyst for every new rule.
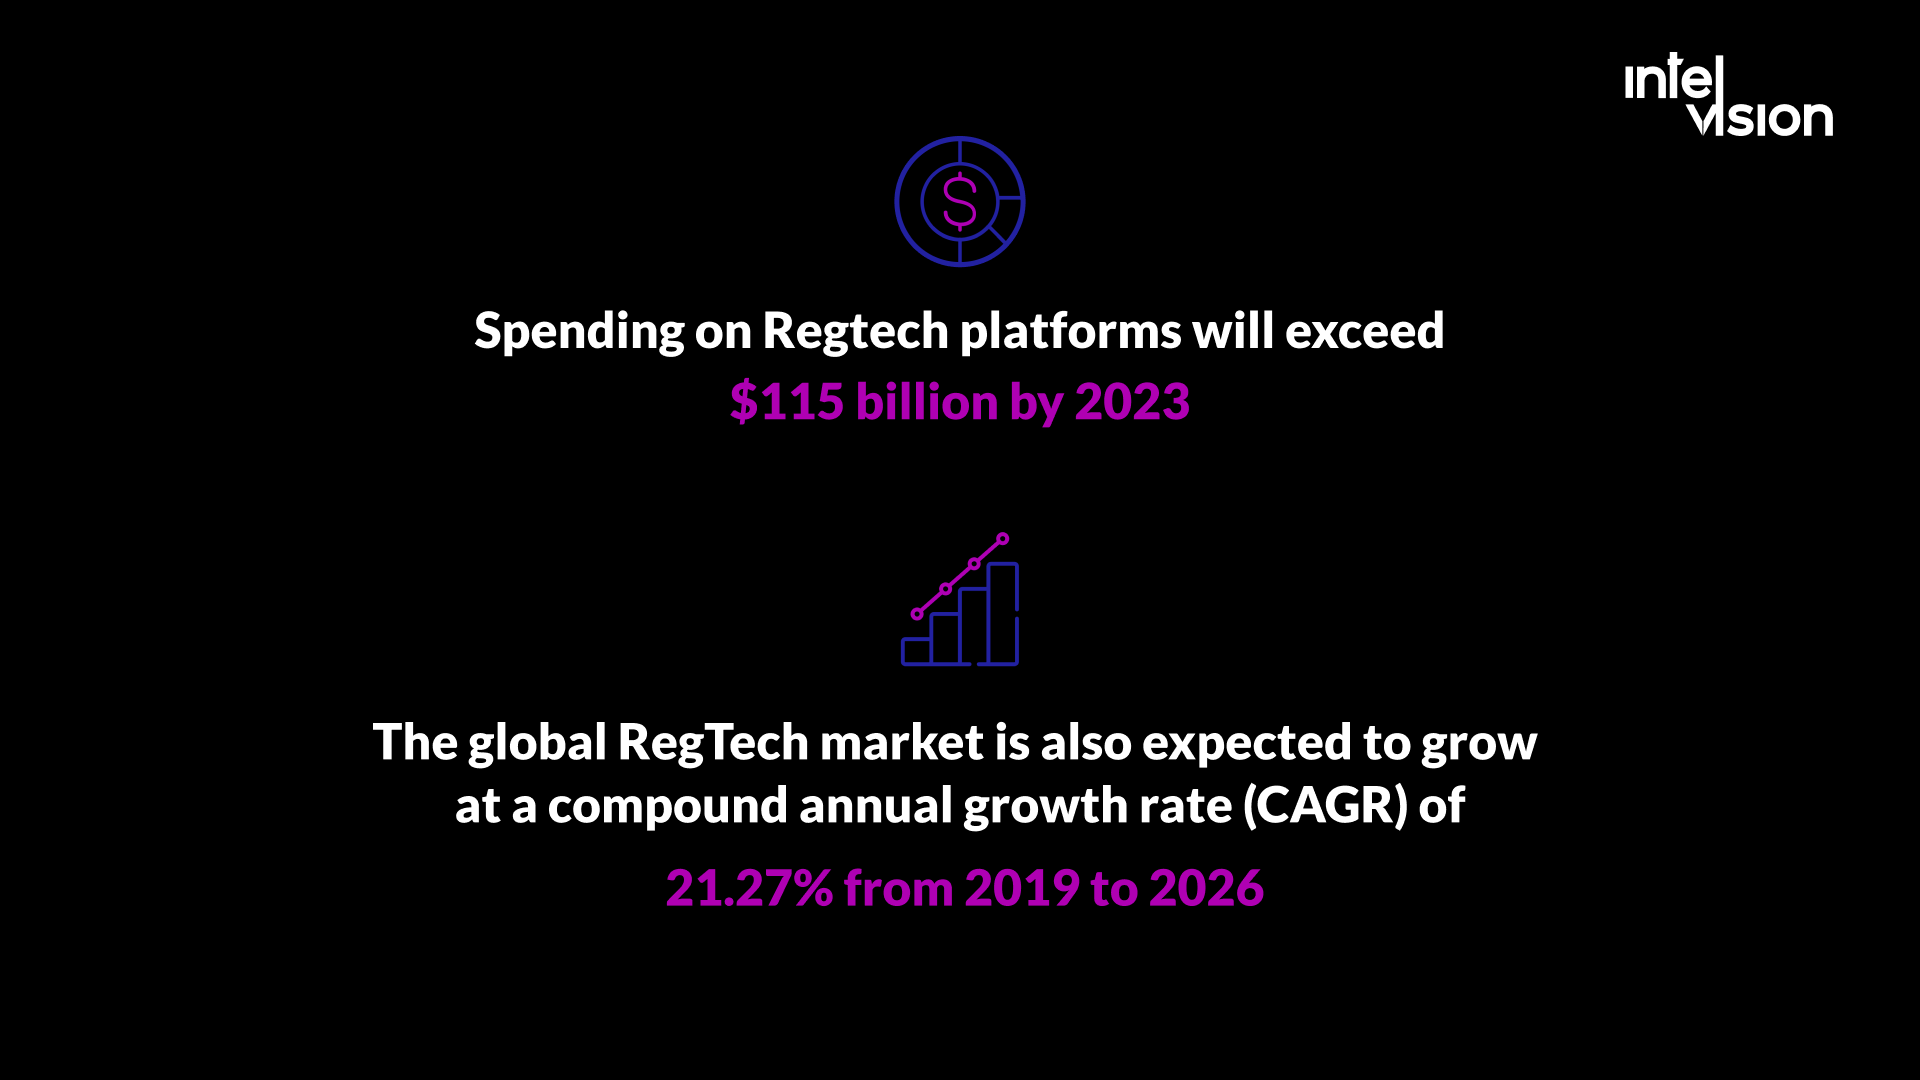
When we first published this article in 2022, analysts were forecasting rapid growth for RegTech. That growth happened: Fortune Business Insights values the RegTech market at $19.06 billion in 2025 and expects $23.43 billion in 2026, with banking, financial services and insurance projected as the largest end-user segment in 2026, with a 25.61% share. Meanwhile, the EU added a new anti-money laundering authority, operational resilience rules, instant payment requirements, crypto licensing and AI regulation.
This updated guide explains what RegTech in banking is, why it matters more in 2026 than it did then, the main use cases, how banks choose and implement it, what it costs, how AI changes it, and the mistakes to avoid.
What RegTech in banking is
RegTech is technology that helps companies comply with the rules and requirements of regulators. The UK Financial Conduct Authority, which did much to establish the term, puts it simply: RegTech applies to new technologies developed to help overcome regulatory challenges in financial services. In banking there are many laws, and new ones appear all the time. RegTech helps banks keep up with that flow using data platforms, cloud computing, automation, machine learning and, increasingly, language models.
The main functions of RegTech are regulatory monitoring, reporting, risk management and compliance. It helps banks identify and reduce risks, cut the cost of compliance and free people for work that needs judgment.
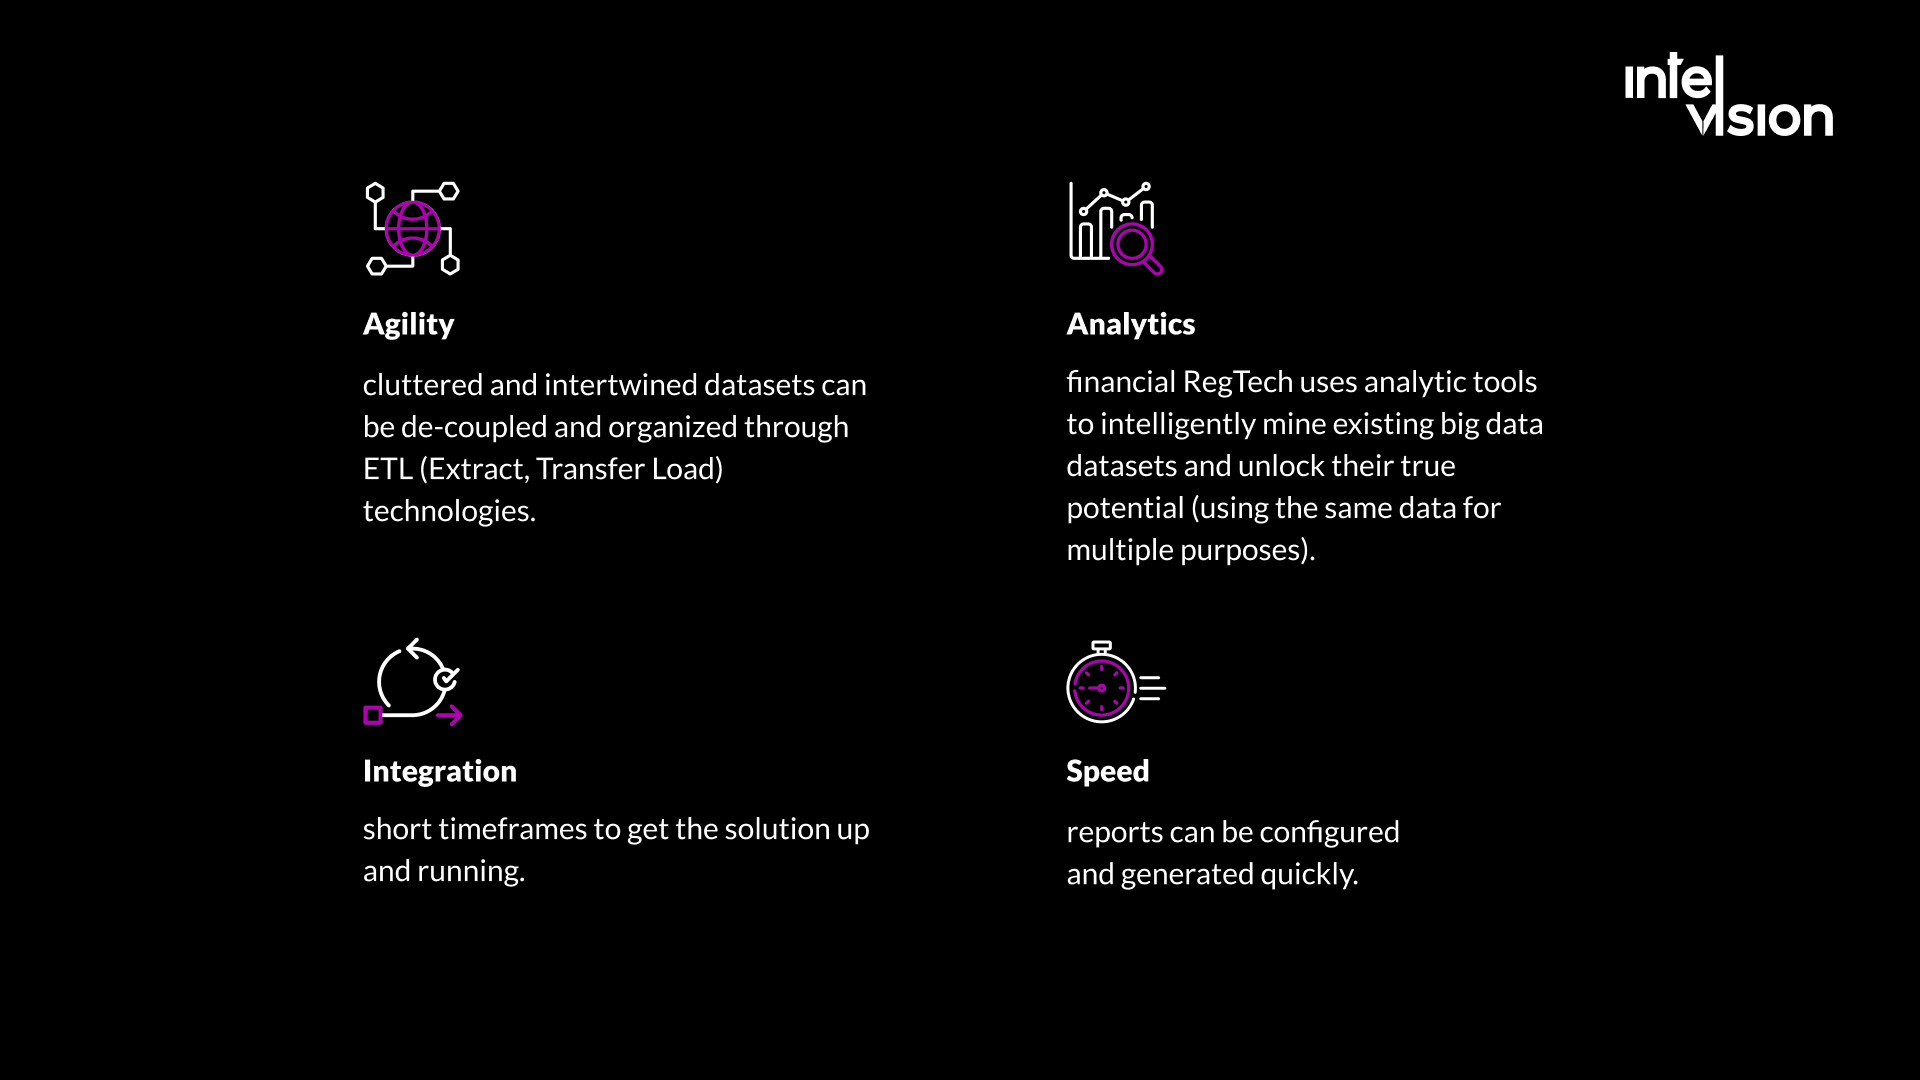
What makes RegTech different from traditional compliance systems? Four characteristics:
- Agility: cluttered and intertwined datasets can be decoupled and organized through ETL (extract, transform, load) pipelines.
- Speed: reports can be configured and generated quickly, often on demand rather than at month end.
- Integration: solutions connect through APIs and can be running in short timeframes.
- Analytics: RegTech uses analytics to mine existing data and reuse the same data for several purposes, such as risk, reporting and fraud.
A short history of RegTech in banking
It started with the financial crisis of 2007 and 2008. Regulators and governments responded with a wave of new rules on capital, liquidity, reporting, conduct and financial crime, and banks had to sharply increase spending on lawyers, consultants and software to keep up.
The concept of RegTech took shape around 2015. A report by the UK Government Chief Scientific Adviser in March 2015 said FinTech could be applied to regulation and compliance, and the FCA was the first regulator to promote the term RegTech. Venture capital followed. Unlike many fintech startups that wanted to replace banks, RegTech companies were seen as partners to the traditional financial system rather than a threat to it.
Since then RegTech has moved from point solutions, such as a tool that checks identity documents, to platforms that cover onboarding, monitoring, reporting and operational resilience. The pressure has not eased: in LexisNexis Risk Solutions' 2023 True Cost of Financial Crime Compliance study, 98% of institutions reported rising financial crime compliance costs.
Why RegTech matters more for banks in 2026
Several regulatory changes now hit banks at the same time, and each one assumes data and processes that are automated:
| Area | What changed | What it demands from systems |
|---|---|---|
| Anti-money laundering | The EU's new authority AMLA, based in Frankfurt, started operations in summer 2025 and is set to begin direct supervision of selected entities in 2028; the single EU AML rulebook applies from 2027 | Consistent customer due diligence, monitoring and reporting across countries |
| Operational resilience | DORA has applied since 17 January 2025, including rules on ICT third-party risk and key contractual provisions | Registers of ICT providers, incident classification and reporting, resilience testing |
| Payments | Under the Instant Payments Regulation of March 2024, euro area banks had to receive instant transfers from January 2025 and send them, with verification of payee, from 9 October 2025 | Real-time screening and name checks in seconds, not batches |
| Crypto-assets | MiCA has applied fully since 30 December 2024, and the longest national transitional periods for existing crypto-asset service providers ended on 1 July 2026 | Licensing-grade controls for banks that offer or support crypto services |
| Artificial intelligence | The AI Act lists creditworthiness evaluation and credit scoring of individuals as high-risk, while excluding fraud detection; the AI Omnibus moved these obligations to 2 December 2027 | Documentation, data governance, logging and human oversight for scoring models |
| Statistical reporting | The ECB is integrating banks' statistical requirements through the Integrated Reporting Framework (IReF) and works with banks on a shared data dictionary, BIRD | Granular, well-defined data that feeds several reports |
Enforcement shows what happens when systems fall behind. In October 2024, FinCEN fined TD Bank a record $1.3 billion, citing, among other failures, insufficient monitoring of peer-to-peer transactions and backlogs of potentially suspicious activity. In July 2025, the FCA fined Monzo £21.1 million, saying it had onboarded customers on limited and sometimes implausible information and had opened accounts for more than 34,000 high-risk customers despite a restriction. In both cases, the failures were in processes that RegTech is built to run.
The main RegTech use cases in banking
Customer onboarding and data validation
RegTech automates the initial verification of customers in line with the regulator's rules: identity documents, biometrics, company registries, ownership structures and bank account checks. Some providers solve single tasks, such as verifying identity documents; others orchestrate the whole onboarding flow with risk scoring.
AML transaction monitoring and sanctions screening
Rules and models flag suspicious patterns, and case management tools help analysts investigate and file reports. With instant payments, screening has to happen in seconds, which makes performance and data quality as important as the rules.
Regulatory reporting automation
RegTech automates the preparation, validation and submission of reports under the applicable rules. The trend, visible in the ECB's integrated reporting work, is toward granular data collected once and reused for many reports.
Operational resilience and ICT third-party risk
Under DORA, banks need a complete view of their ICT providers, contracts and dependencies, and they must classify and report major incidents quickly. Specialized tools keep these registers current and connect them to incident management.
Data protection and cybersecurity
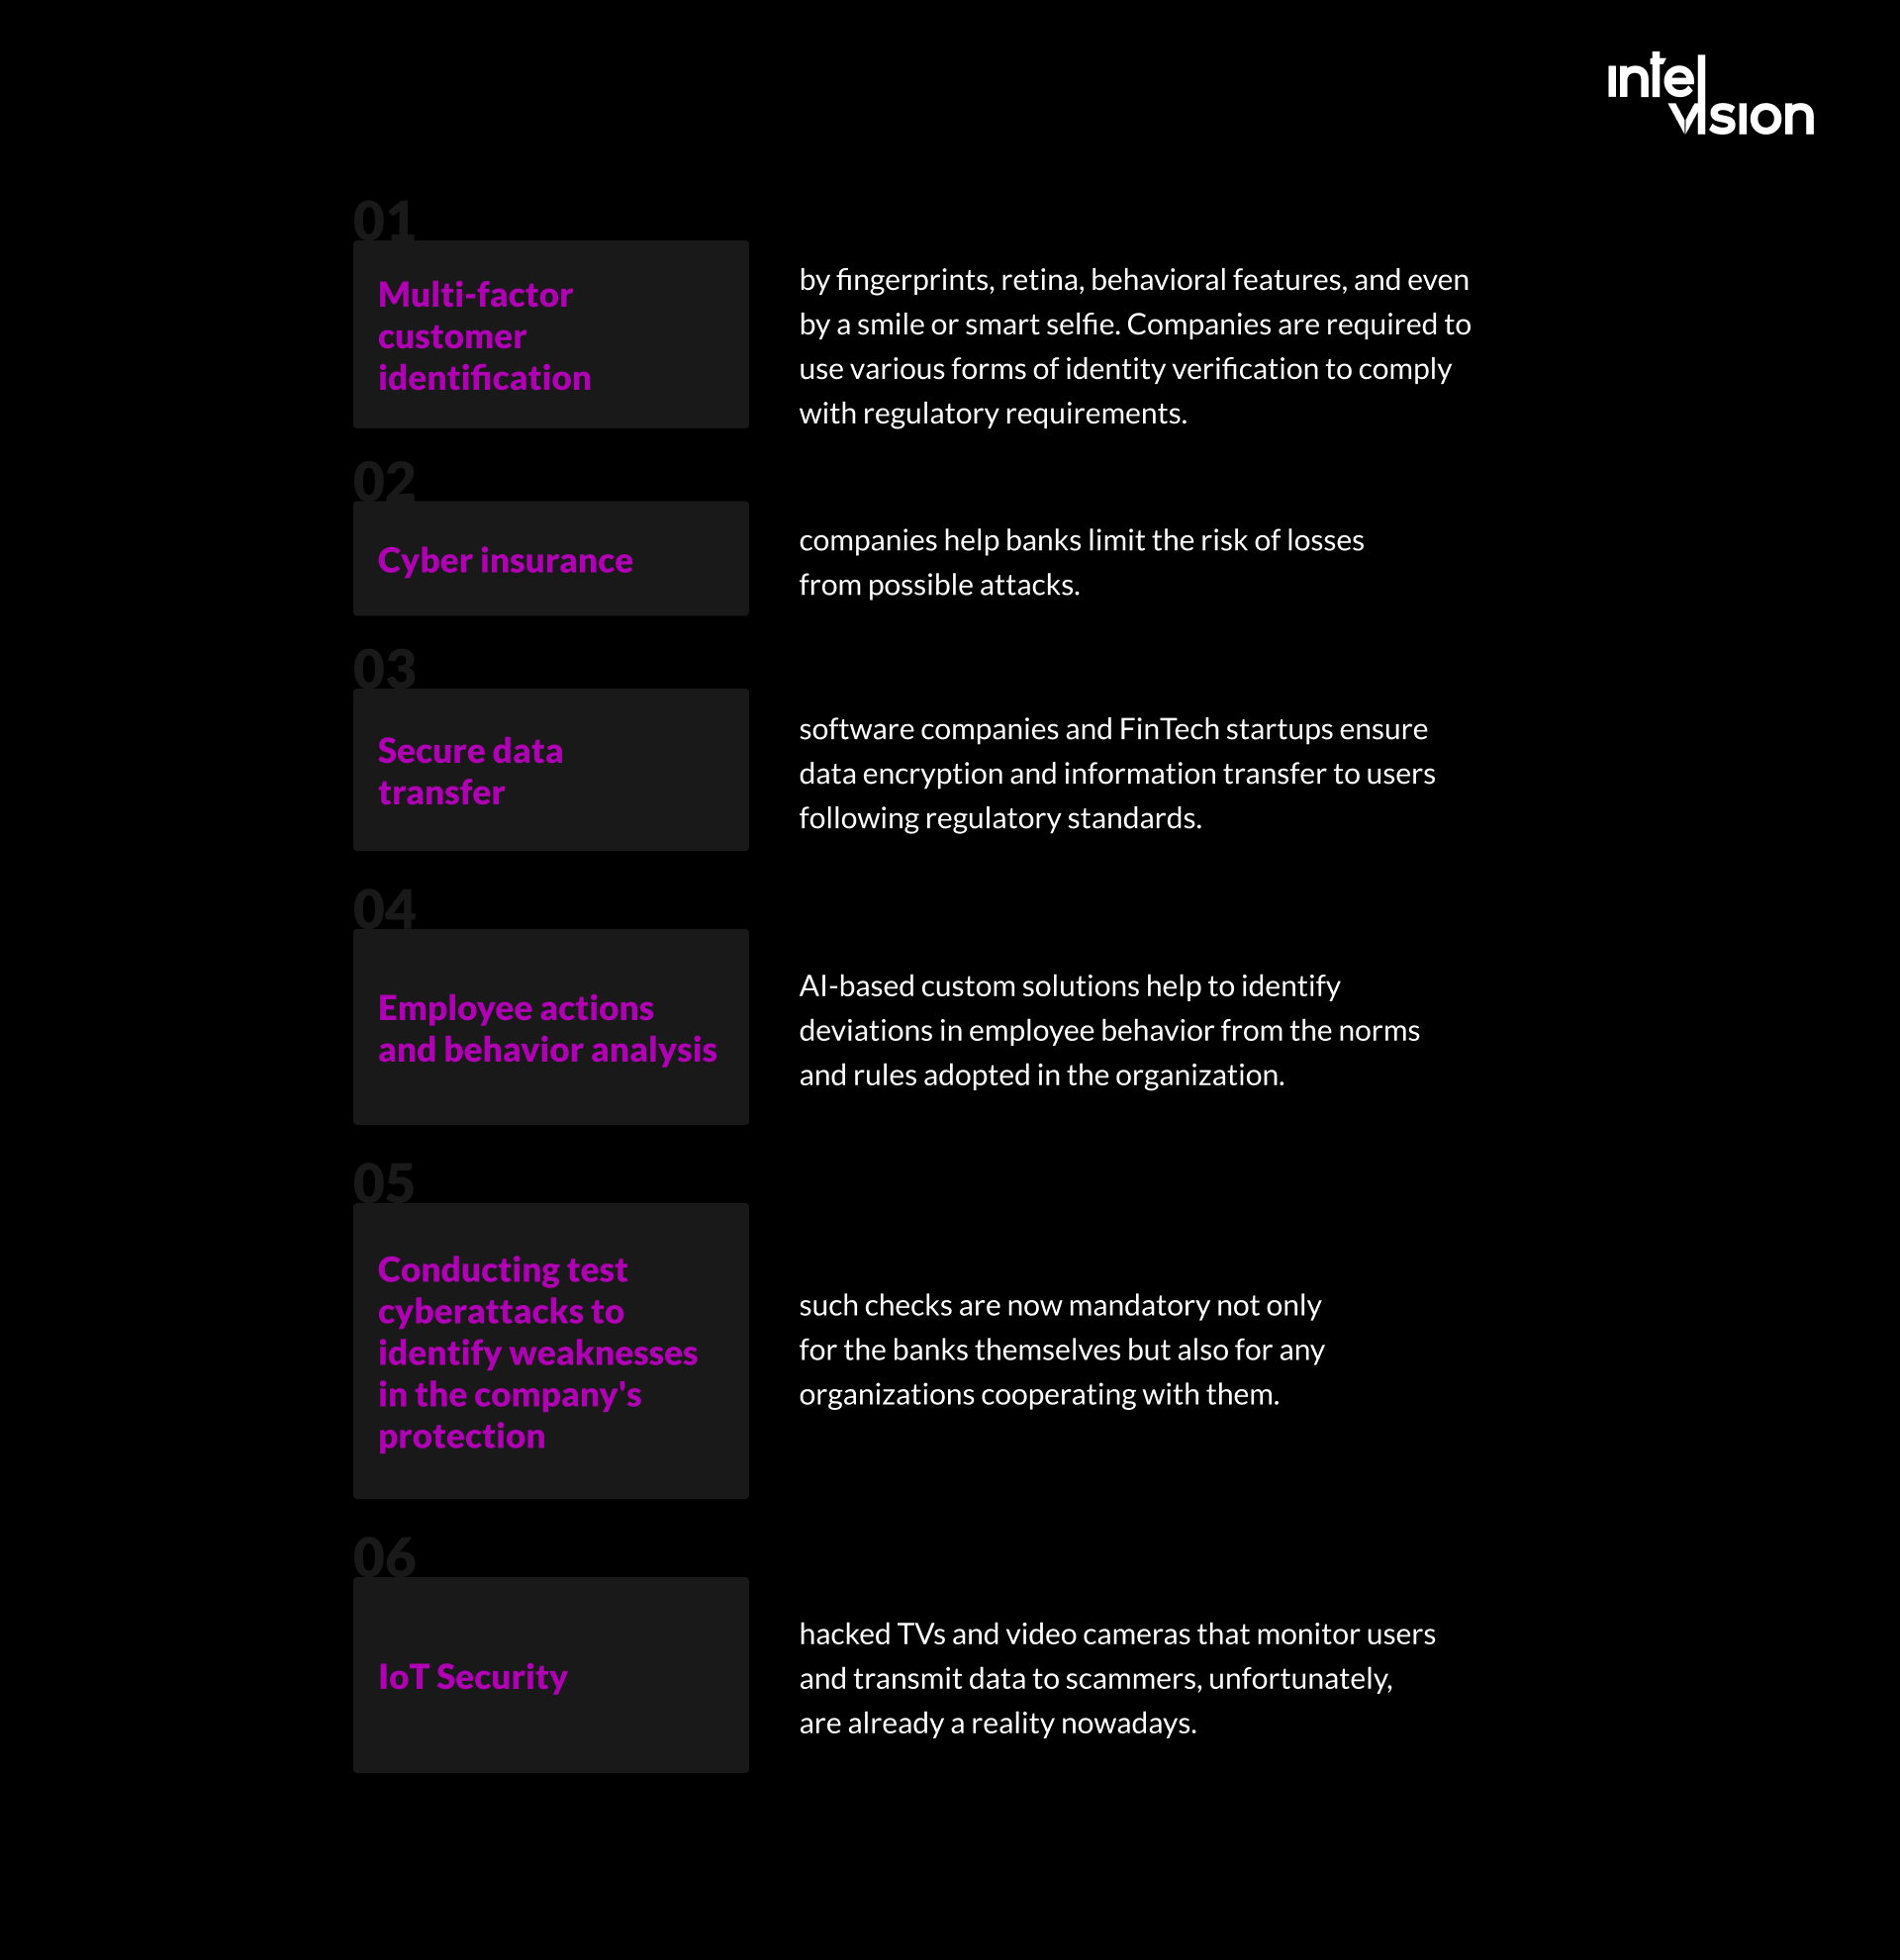
Financial institutions remain prime targets for cyberattacks, and regulators keep raising the bar. RegTech supports banks in several directions:
- Strong customer authentication: multi-factor and biometric identification, from fingerprints to behavioral signals.
- Secure data transfer: encryption and controlled data exchange with customers and partners.
- Employee behavior analysis: AI-based tools that flag deviations from the rules and norms of the organization.
- Resilience testing: test attacks that find weaknesses in the bank's protection, now a formal requirement under DORA for many institutions.
- Privacy compliance: records of processing, consent and breach handling under GDPR, where European regulators issued about €1.2 billion in fines in 2025 according to DLA Piper.
Regulatory change management
As soon as new rules are published, RegTech tools help identify what changed, which obligations and controls are affected, and who must act. Software does not comply automatically, but it makes sure nothing is missed.
Conduct and communications surveillance
Monitoring of trading, communications and complaints helps banks detect market abuse and unfair treatment of customers early.
The main benefits of RegTech for banks
The key difference between traditional compliance systems and RegTech is agility. Traditional solutions are robust and designed to deliver locked-down requirements, but they can be inflexible and often require development in a proprietary language for every change.
Most RegTech solutions are cloud-based: data is maintained, managed and backed up remotely, under the bank's security and outsourcing rules. Cloud delivery gives flexibility in how data is accessed and shared, performance and scalability as volumes grow, and strong security with encryption in transit and at rest, and you pay for what you use. Banks considering a broader move should read our article on cloud banking.
The benefits banks report most often:
- Transparency: risk monitoring built into operations gives a real-time view of compliance status, so issues surface before they become findings or fines.
- Cost efficiency: automating repetitive checks reduces the manual effort per customer, transaction and report.
- Speed: faster onboarding and reporting improve both customer experience and regulatory timeliness.
- Consistency: rules applied by software are applied the same way every time, with an audit trail.
- Adaptability: configurable rules and thresholds let compliance teams respond to change without waiting for a release.
Build, buy or integrate: how banks choose RegTech
| Option | When it fits | Watch out for |
|---|---|---|
| Buy a platform | Standard processes, such as sanctions screening or common regulatory reports, where vendors maintain rule content | Lock-in, per-volume pricing, limited fit with your data |
| Integrate specialist APIs | Single functions such as identity verification or KYC checks, inside your own onboarding flow | Vendor outages, data residency, DORA third-party obligations |
| Build custom | Your products, risk models or data are specific, or you need full control over logic and audit trails | Ongoing ownership, model validation and the need for strong engineering |
| Combine | Most mid-size banks and fintechs: buy commodity checks, build orchestration, scoring, case management and reporting | Clear ownership of the end-to-end process |
The combined approach is what we used for a digital lender in the EU: a third-party KYC API for checks, wrapped in a custom scoring engine, compliance dashboard, case logging and ERP and CRM synchronization.
What RegTech costs and how to build the business case
Costs come from licenses or usage fees, implementation and integration, data work, internal time, and running and validating the system. For custom work, the cost is team size times duration; a focused onboarding or monitoring platform is usually built by a small cross-functional team rather than a department.
The business case should rest on numbers you can measure before and after:
- time to onboard a customer, and the share abandoned during onboarding;
- analyst hours per alert, per case and per report;
- share of alerts that turn out to be false positives;
- time to produce and correct regulatory reports;
- audit and supervisory findings, and the fine exposure they represent.
Our own projects show the order of magnitude that is possible. For the EU lender, onboarding time fell from 48 hours to 2 and compliance staffing needs fell by 40%. For a regulated payments company in the DACH region, a real-time payments dashboard built on Kafka, TimescaleDB, Node.js and React cut compliance report generation from two days to minutes, improved anomaly response four times and covers 100% of live transaction flows.
How to implement RegTech in a bank, step by step
- Pick one process with a clear pain, such as onboarding backlogs, alert overload or a slow regulatory report.
- Map the obligations behind it and the controls that meet them.
- Map the data: sources, owners, quality and gaps. Most RegTech projects are data projects.
- Decide build, buy or combine for each part of the process.
- Check third-party and data rules: DORA contract terms, outsourcing notifications where required, GDPR and data location.
- Build or configure in small releases, with compliance staff testing each one.
- Run in parallel with the existing process and compare results before switching over.
- Document for supervisors: logic, thresholds, model validation and audit trails.
- Measure and extend to the next process.
If you need engineers with financial services experience to do this work inside your team, our list of staff augmentation companies for fintech compares the options.
How AI is changing RegTech in banking
AI is now used across RegTech:
- Alert triage: models rank AML alerts so analysts work on the riskiest first.
- Entity resolution: matching names, companies and ownership chains across messy data.
- Document understanding: reading identity documents, contracts, financial statements and source-of-funds evidence.
- Regulatory change: summarizing new rules and mapping them to internal policies and controls.
- Investigation support: drafting case narratives and reports for an analyst to review.
The constraint is accountability. Supervisors expect banks to explain decisions, and the AI Act treats credit scoring of individuals as high-risk. The safest designs keep deterministic rules where money and legal duties are involved, use AI to prepare and prioritize, log every input and output, and leave the decision with a named person.
RegTech key trends for 2026
KYC and financial crime under one EU rulebook
More customers bank online, and payments settle in seconds. Knowing your customer remains the foundation of financial crime prevention, and with AMLA and the single rulebook, banks operating in several EU countries will need consistent, data-driven due diligence across all of them.
Real-time compliance for real-time payments
Instant payments and verification of payee push screening, fraud checks and name matching into the payment flow itself. Batch processes overnight are no longer enough.
Crypto moves from enforcement to licensing
Regulators have focused on crypto for years; in 2021 BitMEX agreed to a $100 million civil penalty with the CFTC, partly for AML failures. With MiCA fully in force, banks and crypto firms in the EU now need licensing-grade compliance tools rather than ad hoc controls.
ESG reporting, simplified
Environmental, social and governance reporting remains on the agenda, but the EU has simplified and postponed parts of its sustainability reporting rules. Banks still need ESG data about their own operations and their borrowers for risk management and disclosures.
Operational resilience as a permanent program
DORA turned resilience into an ongoing duty, with registers, incident reporting and testing. Expect RegTech and security tooling to converge.
AI governance inside the bank
Banks need an inventory of AI systems, risk classification and documentation, especially for credit decisions. This is becoming a RegTech category of its own.
Common mistakes banks make with RegTech
- Automating a broken process. If the manual process is unclear, software makes the confusion faster.
- Underestimating data work. Poor customer and transaction data produces poor alerts, whatever the tool.
- Tuning for fewer alerts instead of better ones. Supervisors will ask why thresholds changed.
- Forgetting the auditors. If logic and decisions are not documented and logged, the system creates a new finding.
- Ignoring third-party rules. A RegTech vendor is an ICT provider under DORA, with contract and oversight requirements.
- Leaving compliance staff out of design. The people who use the system daily know where the real friction is.
A RegTech readiness checklist for banks and fintechs
Before you start a RegTech project, check where you stand:
- You have an up-to-date register of the obligations that apply to each product and country you operate in.
- Every key control has an owner, and you know which system produces its evidence.
- Customer, account and transaction data have clear definitions and owners, and you know their quality.
- You know which compliance processes are still run in spreadsheets or email, and how many hours they take.
- Your contracts with RegTech and other ICT providers contain the terms DORA requires, if you are a financial entity.
- Thresholds, rules and models are documented, versioned and validated, with a record of who changed what and why.
- You have an inventory of AI systems used in compliance and credit decisions, with a risk classification for each.
- Instant payment flows run screening and verification of payee within the time limits, with fallback procedures.
- Compliance, risk, IT and the business share one roadmap for regulatory change, instead of separate project lists.
Each unchecked item is a candidate for the first RegTech project. Start with the one where manual effort and regulatory exposure overlap most.
How Intelvision helps financial companies with custom RegTech
Intelvision builds custom software for financial companies, integrates specialist RegTech services, and places senior engineers inside teams that are already building. Our published fintech work includes the compliance automation platform for the EU lender and the real-time payments dashboard for the DACH payments provider described above, as well as Finsemble, a desktop application framework for fintech in the US. See our fintech page for more, and our guide to regulatory compliance software for the wider, cross-industry view.
RegTech plays a central role in the future of risk and compliance management for financial services. Banks that build it into their operations, rather than bolting it on before each audit, manage risk more efficiently and spend less of their budget on manual compliance work.
Sources
- Fortune Business Insights: RegTech market
- FCA: RegTech
- Wikipedia: Regulatory technology
- LexisNexis Risk Solutions: True Cost of Financial Crime Compliance Global Study, 2023
- AMLA: About AMLA
- EIOPA: Digital Operational Resilience Act (DORA)
- Wikipedia: Single Euro Payments Area
- ESMA: Markets in Crypto-Assets Regulation (MiCA)
- EU AI Act: Annex III
- European Commission: AI Act regulatory framework
- ECB: Reporting, IReF and BIRD
- FinCEN: FinCEN Assesses Record $1.3 Billion Penalty against TD Bank
- FCA: FCA fines Monzo £21m for failings in financial crime controls
- DLA Piper: GDPR Fines and Data Breach Survey, January 2026
- CFTC: BitMEX ordered to pay $100 million (2021)
- European Commission: Corporate sustainability reporting
Read Intelvision often? Add us as a preferred source in Google Search.
Add to preferred sources